Share your email and we'll share the latest news
Exclusive economic intelligence, political and business coverage
Thursday, November 12 2026
Thursday, November 12 2026
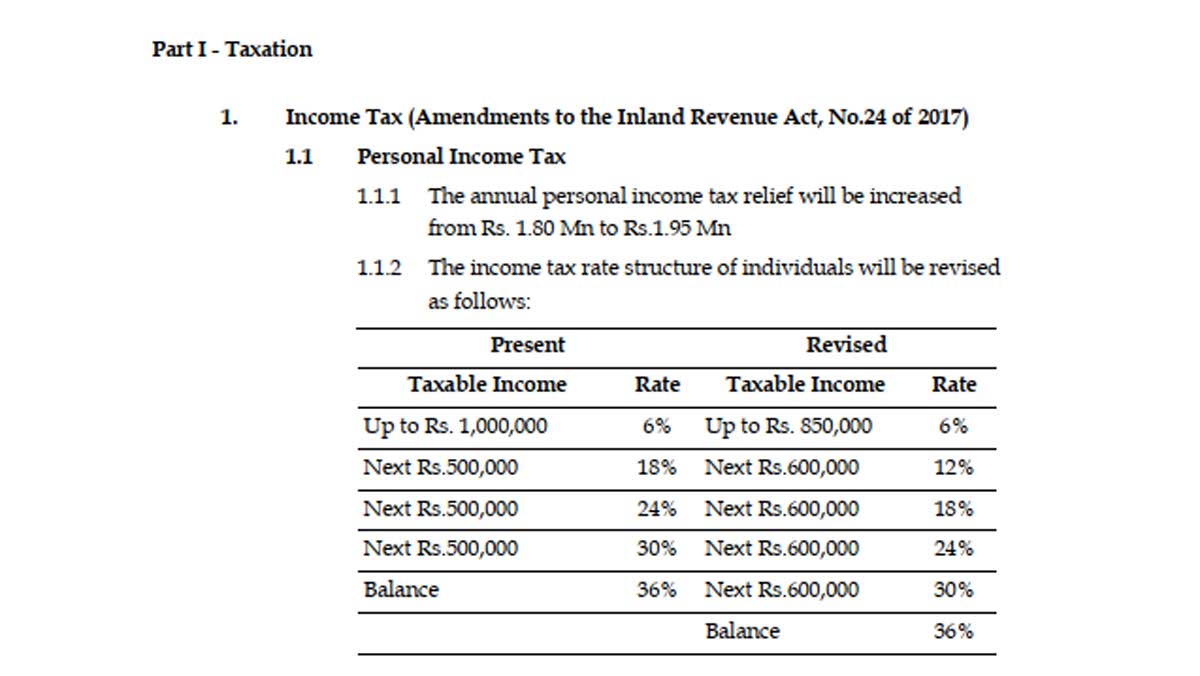
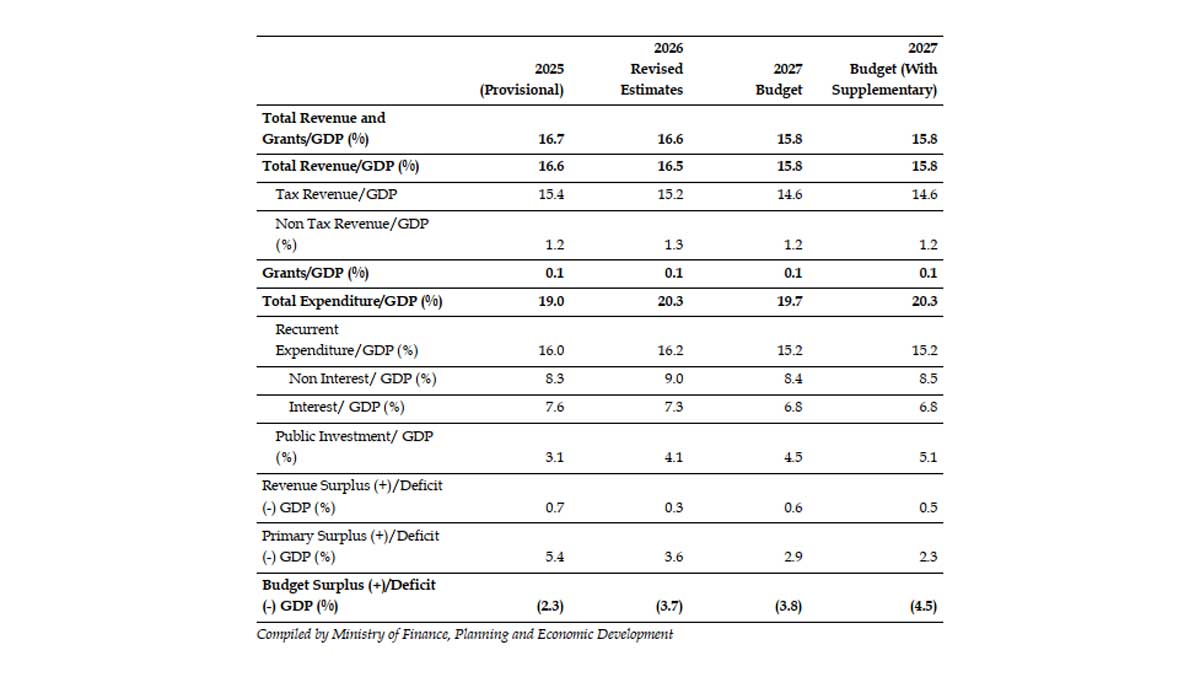
MONETABRIEF - Sri Lanka President Anura Kumara Dissanayake has proposed the following tax changes in the 2027 budget, outside of personal income tax reduction.
Enhanced Capital Allowance for BOI approved Enterprises
BOI approved enterprises investing a minimum amount of USD 3 Million in export-oriented manufacturing or tourism development will be permitted to opt for enhanced capital allowance equivalent to 200% of qualifying capital expenditure, subject to the conditions that;
- In the case of manufacturing and tourism (other than hotels), investment should be made within 3 years;
- For hotels, investment should be made within 5 years
- Existing capital allowance under Fourth Schedule or enhanced capital allowance under Second Schedule will not be allowed.
1.3 Broadening the Scope of “capital asset” Definition The definition of “capital asset” under section 195 of the Inland Revenue Act, No. 24 of 2017, to include the following assets within the scope of Capital Gains Tax:
- Digital and virtual assets, including cryptocurrencies;
- Telecommunications, broadcasting and other similar licences and rights having commercial value;
- Gems, jewellery, precious metals and other valuable movable assets exceeding a prescribed monetary threshold.
Value Added Tax (VAT) [Amendments to the Value Added Tax Act, No.14 of 2002] 2.1 Exemption of Books and Printed Material<.b>
Import or supply of books and printed material classified under the Harmonized Commodity Description and coding System Numbers for Custom purposes will be exempted from VAT as follows:
HS Code Description
4820.20 Exercise books
4901.99.10 Printed books
4901.91 Dictionaries and encyclopedias 4903.00 Children’s picture, drawing or coloring books
4901.10 Printed matter in single sheets
4904.00.10 Music books /printed music
4904.00.90 Printed music other than in book form
Removal of Exemption
VAT exemption applicable on following items will be removed.
HS Code Description
0511.91.20 Artemia eggs
1404.90.93 Coconut coir pith
Revision of the basis of calculation of VAT on Film Tickets
The VAT liability of film producers, distributors, the National Film Corporation and cinema hall operators will be determined based on the respective share of cinema ticket revenue received or appropriated by each party. The basis for calculating VAT liability will be revised to apply ticket value after Entertainment Tax but before VAT.
2.4 Amendment of the Definition of “Eligible Exporter”
The definition of the term “eligible exporter” will be amended to recognize the Newly VAT registered persons as eligible exporters where, more than 80% of their turnover during the preceding 06 months has been derived from exports.
2.5 Specifying Exchange Rate for VAT on Supplies made for Foreign Currency
The indicative exchange rate published by the Central Bank of Sri Lanka, as may be specified by the CGIR will be applied in converting foreign currency into Sri Lankan rupees for VAT purposes.
2.6 Validity of Electronic Tax Invoices
The digital or electronic invoices will be recognized as legally valid similarly as paper-based invoices. The format, particulars, technical and procedural requirements of electronic invoice will be specified by the CGIR, by order published in the Gazette.
Social Security Contribution Levy (SSCL) [Amendments to the Social Security Contribution Levy Act, No.25 of 2022]
Exemption on the Supply of Bunker Fuel to Ships
Amendments will be introduced to expressly exempt the bunker fuel supplied to ships engaged in international transportation from SSCL.
4. Simplification of the Tax Structure Applicable to the Betting and Gaming Industry
Amendments will be introduced to Betting and Gaming Levy Act, No. 40 of 1988 and other relevant tax laws to establish a simplified, transparent and coherent tax structure for the betting and gaming industry, which will be easy to administer and comply with.
5. Revision of Special Commodity Levy (SCL)
SCL applicable on the import of certain essential food Items will berevised with effect from November 13, 2026, as follows:
- SCL will be reduced to Rs. 10 per Kilogram for sprats and Maldive fish;
- SCL will be reduced by Rs. 50 per Kilogram for powdered and unpowdered dried chilies;
- SCL will be increased by Rs. 10 per Kilogram for sugar.
6. Phased Reduction of PARA-Tariffs Following revisions will be made as a part of the phased removal of ParaTariffs:
6.1 Removal of Ports and Airports Development levy (PAL) Effective from January 1, 2027, the Port and Airport Development Levy will be removed on the importation of newsprint and batteries used for solar energy storage. 6.2 CESS
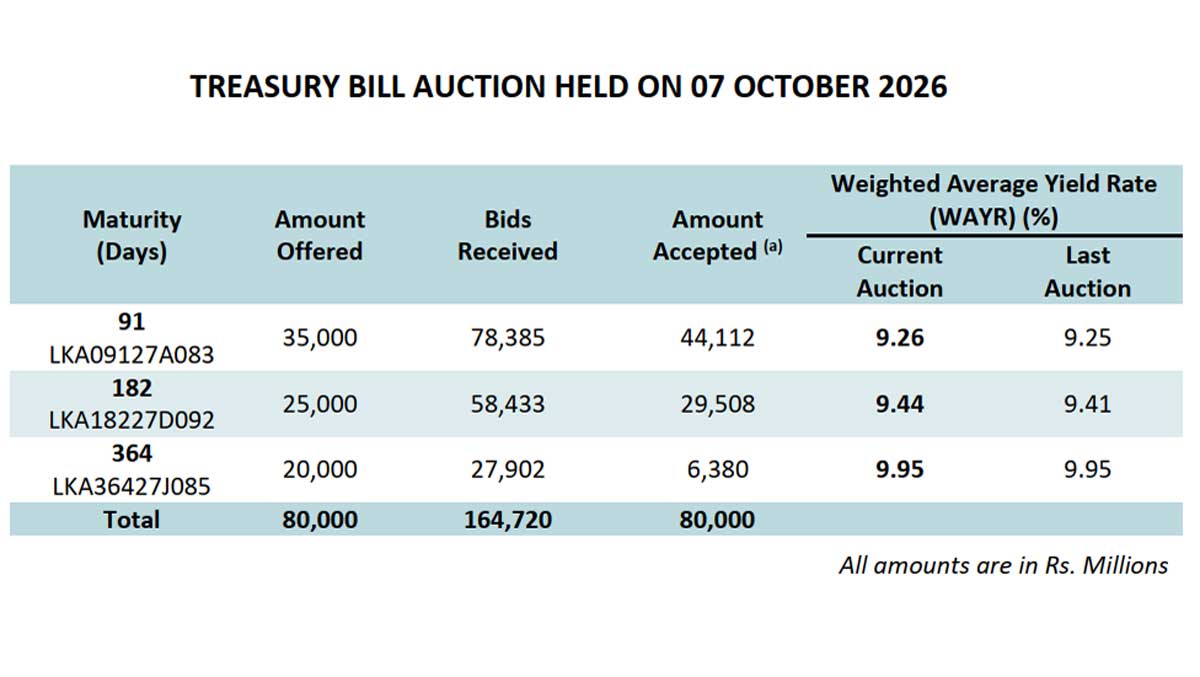
| 3 month bill | 9.26% | 1bp ▲ |
| 12-m bill | 9.95% | 2bp - |
| Gold (Ounce) | $4015 | - ▼ |
Comments
Be the first person to comment and join the debate