Share your email and we'll share the latest news
Exclusive economic intelligence, political and business coverage
Tuesday, October 27 2026
Tuesday, October 27 2026
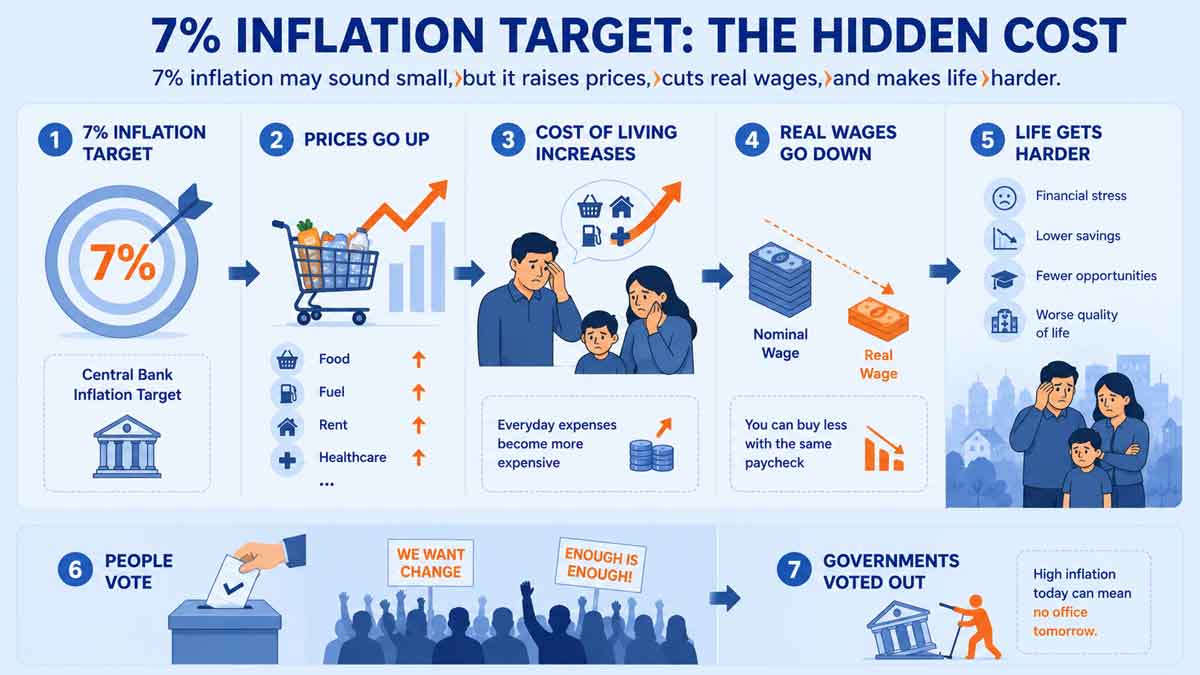
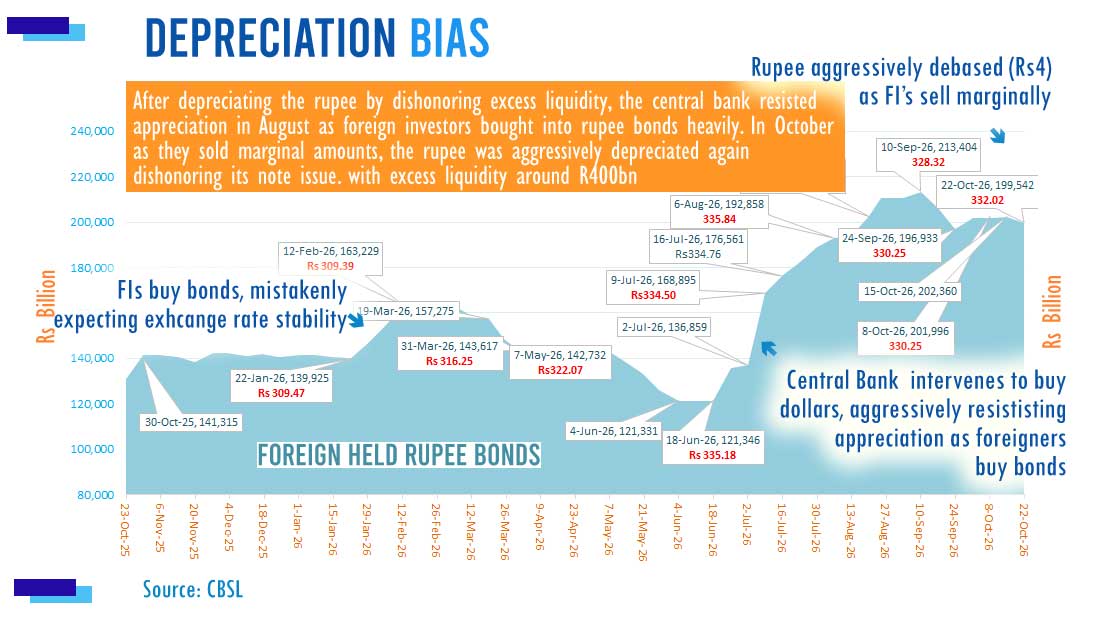 INFLATION BIAS: Since the end of the war in particular, macro-economists have followed skewed inflation biased exchange rate policy violating democratic norms
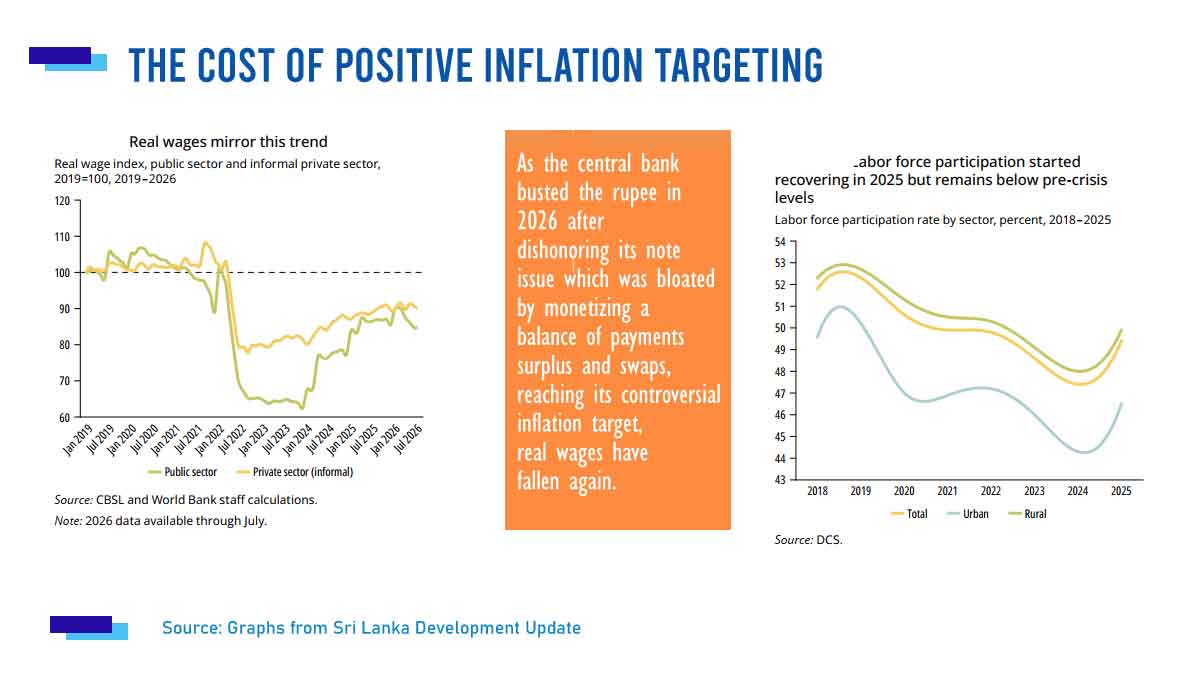
MONETABRIEF – Sri Lanka's central bank has depreciated the rupee dishonoring its note issue, which has been bloated by previous dollar purchases over in recent weeks, as foreign investors exited rupee bonds in marginal amounts.
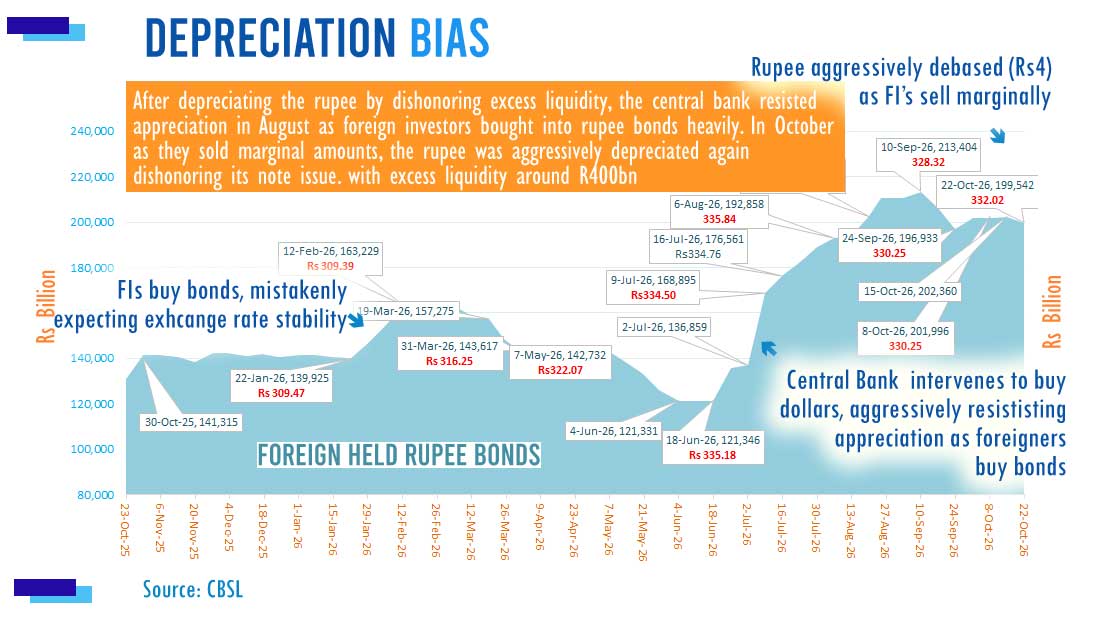
Foreign investor holdings in rupee bonds peaked at 213 billion rupees on 10 September 2026, when the rupee was at around 328 to the US dollar.
Two weeks later, the rupee has been debased to 332 to the US dollar. The central bank previously bloated its note issue buying dollars, as foreign investors aggressively bought into rupee bonds.
The rupee was kept at 335 to the US dollar as foreign investor holdings climbed from 121 billion rupees to 192 billion, showing the inflation and depreciation of the central bank, as it monetized a balance of payments surplus aggressively.
As the central bank bought dollars heavily with printed money (expanding the note issue) excess liquidity surged.
Interest rates then fell, immediately after a rate hike, showing why a pegged exchange rate central bank which intervenes in forex markets to build reserves (exchange rate policy) cannot also target interest rates (monetary policy) exposing a key flaw in the operating framework of so-called 'flexible' inflation targeting.
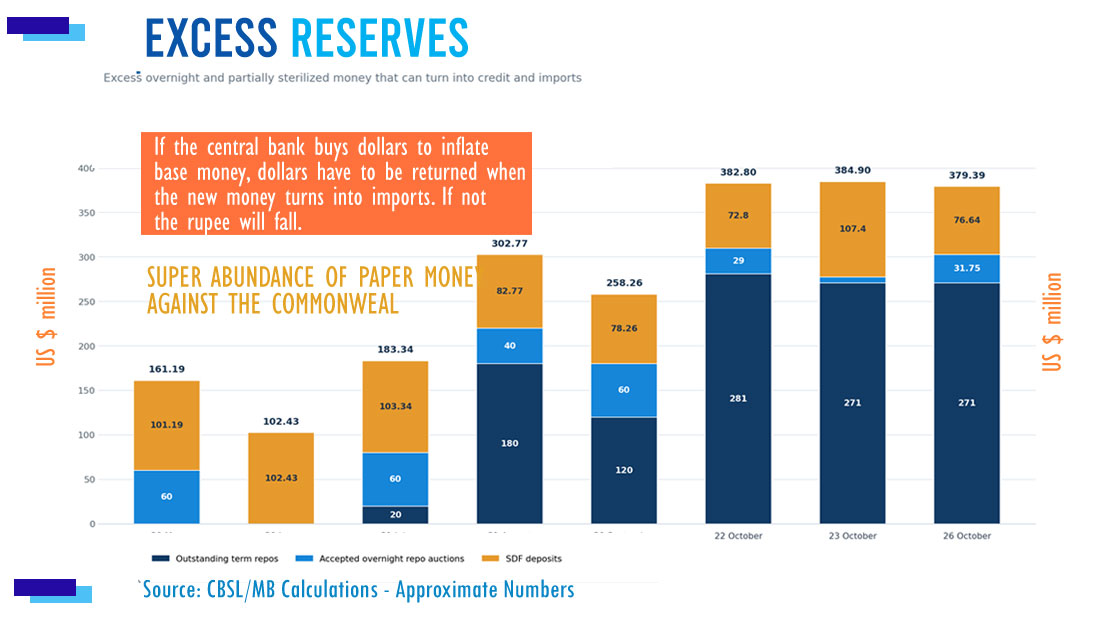
The excess liquidity from monetizing the BoP rose to almost 400 billion in October and it was partially sterilized overnight and through term repos.
When foreign investors exit, banks can terminate the term repos and use the liquidity to buy the bond from exiting investors without crowding out other credit and imports.
To maintain monetary stability and social cohesion the central bank then has to return the dollars and honor the new money it created and left unsterilized or partially sterilized on a consistent rule.
When it dishonors the notes, under flexible exchange rate doctrine, the rupee the rupee depreciates.
From 2015 to 2019 after printing money by outright purchases of bonds, violating a bills only policy and monetizing Hambantota Port sales proceeds the rupee was debased and foreign investors were put to flight. Then foreign investors were blamed for the instability.
Analysts and the Committee on Public Finance have called for the Treasury to buy dollars to build reserves to prevent macro-economists from monetizing the balance of payments, which can then be dishonored to debase money and push up the cost of living.
For many decades the central banks blamed the budget deficit for foreign exchange troubles, but the note issue was dishonored to depreciate the rupee in 2026 amid a budget surplus exposing a 74 year old myth spread by macro-economists against.
Then an 'external shock' was blamed as exchange rates in Dubai, Qatar, Oman and Saudi Arabia, where monetary authorities follow classical economics remained rock solid.
There have been calls for many years to curb the central bank's discretion which has been institutionalized under 'flexible' exchange rate and 'flexible' inflation targeting, as such practices against democratic norms which require the state to operate under predictable rules.
The discretion was used to depreciate and prevent appreciation in skewed exchange rate policy for many years.
"Nothing distinguishes more clearly a free country from a country under arbitrary government than the observance in the former of the great principles known as the Rule of Law," explained classical economist Friedrich A Hayek.
"Stripped of technicalities this means that government in all its actions is bound by rules fixed and announced beforehand – rules that make it possible to foresee with fair certainty how the authority will use its coercive powers in given circumstances and to plan one’s individual affairs on the basis of this knowledge."
The 333 to the US dollar level was the intervention rate the central bank used during the currency collapse of April to June, after dishonoring the notes from 309 to the US dollar in January. How the rate has been arrived at has not been disclosed.
Dollars were sold at the rate without an active spot market. (Colombo/Oct26/2026)
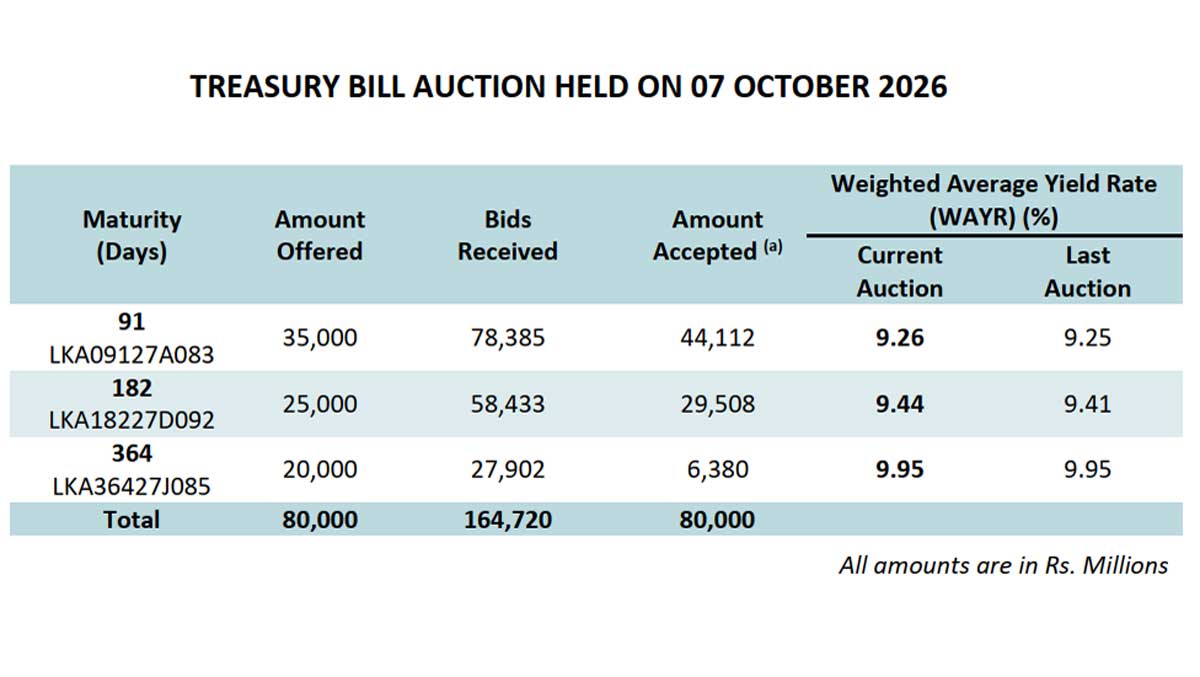
| 3 month bill | 9.26% | 1bp ▲ |
| 12-m bill | 9.95% | 2bp - |
| Gold (Ounce) | $4015 | - ▼ |

Comments
Be the first person to comment and join the debate